

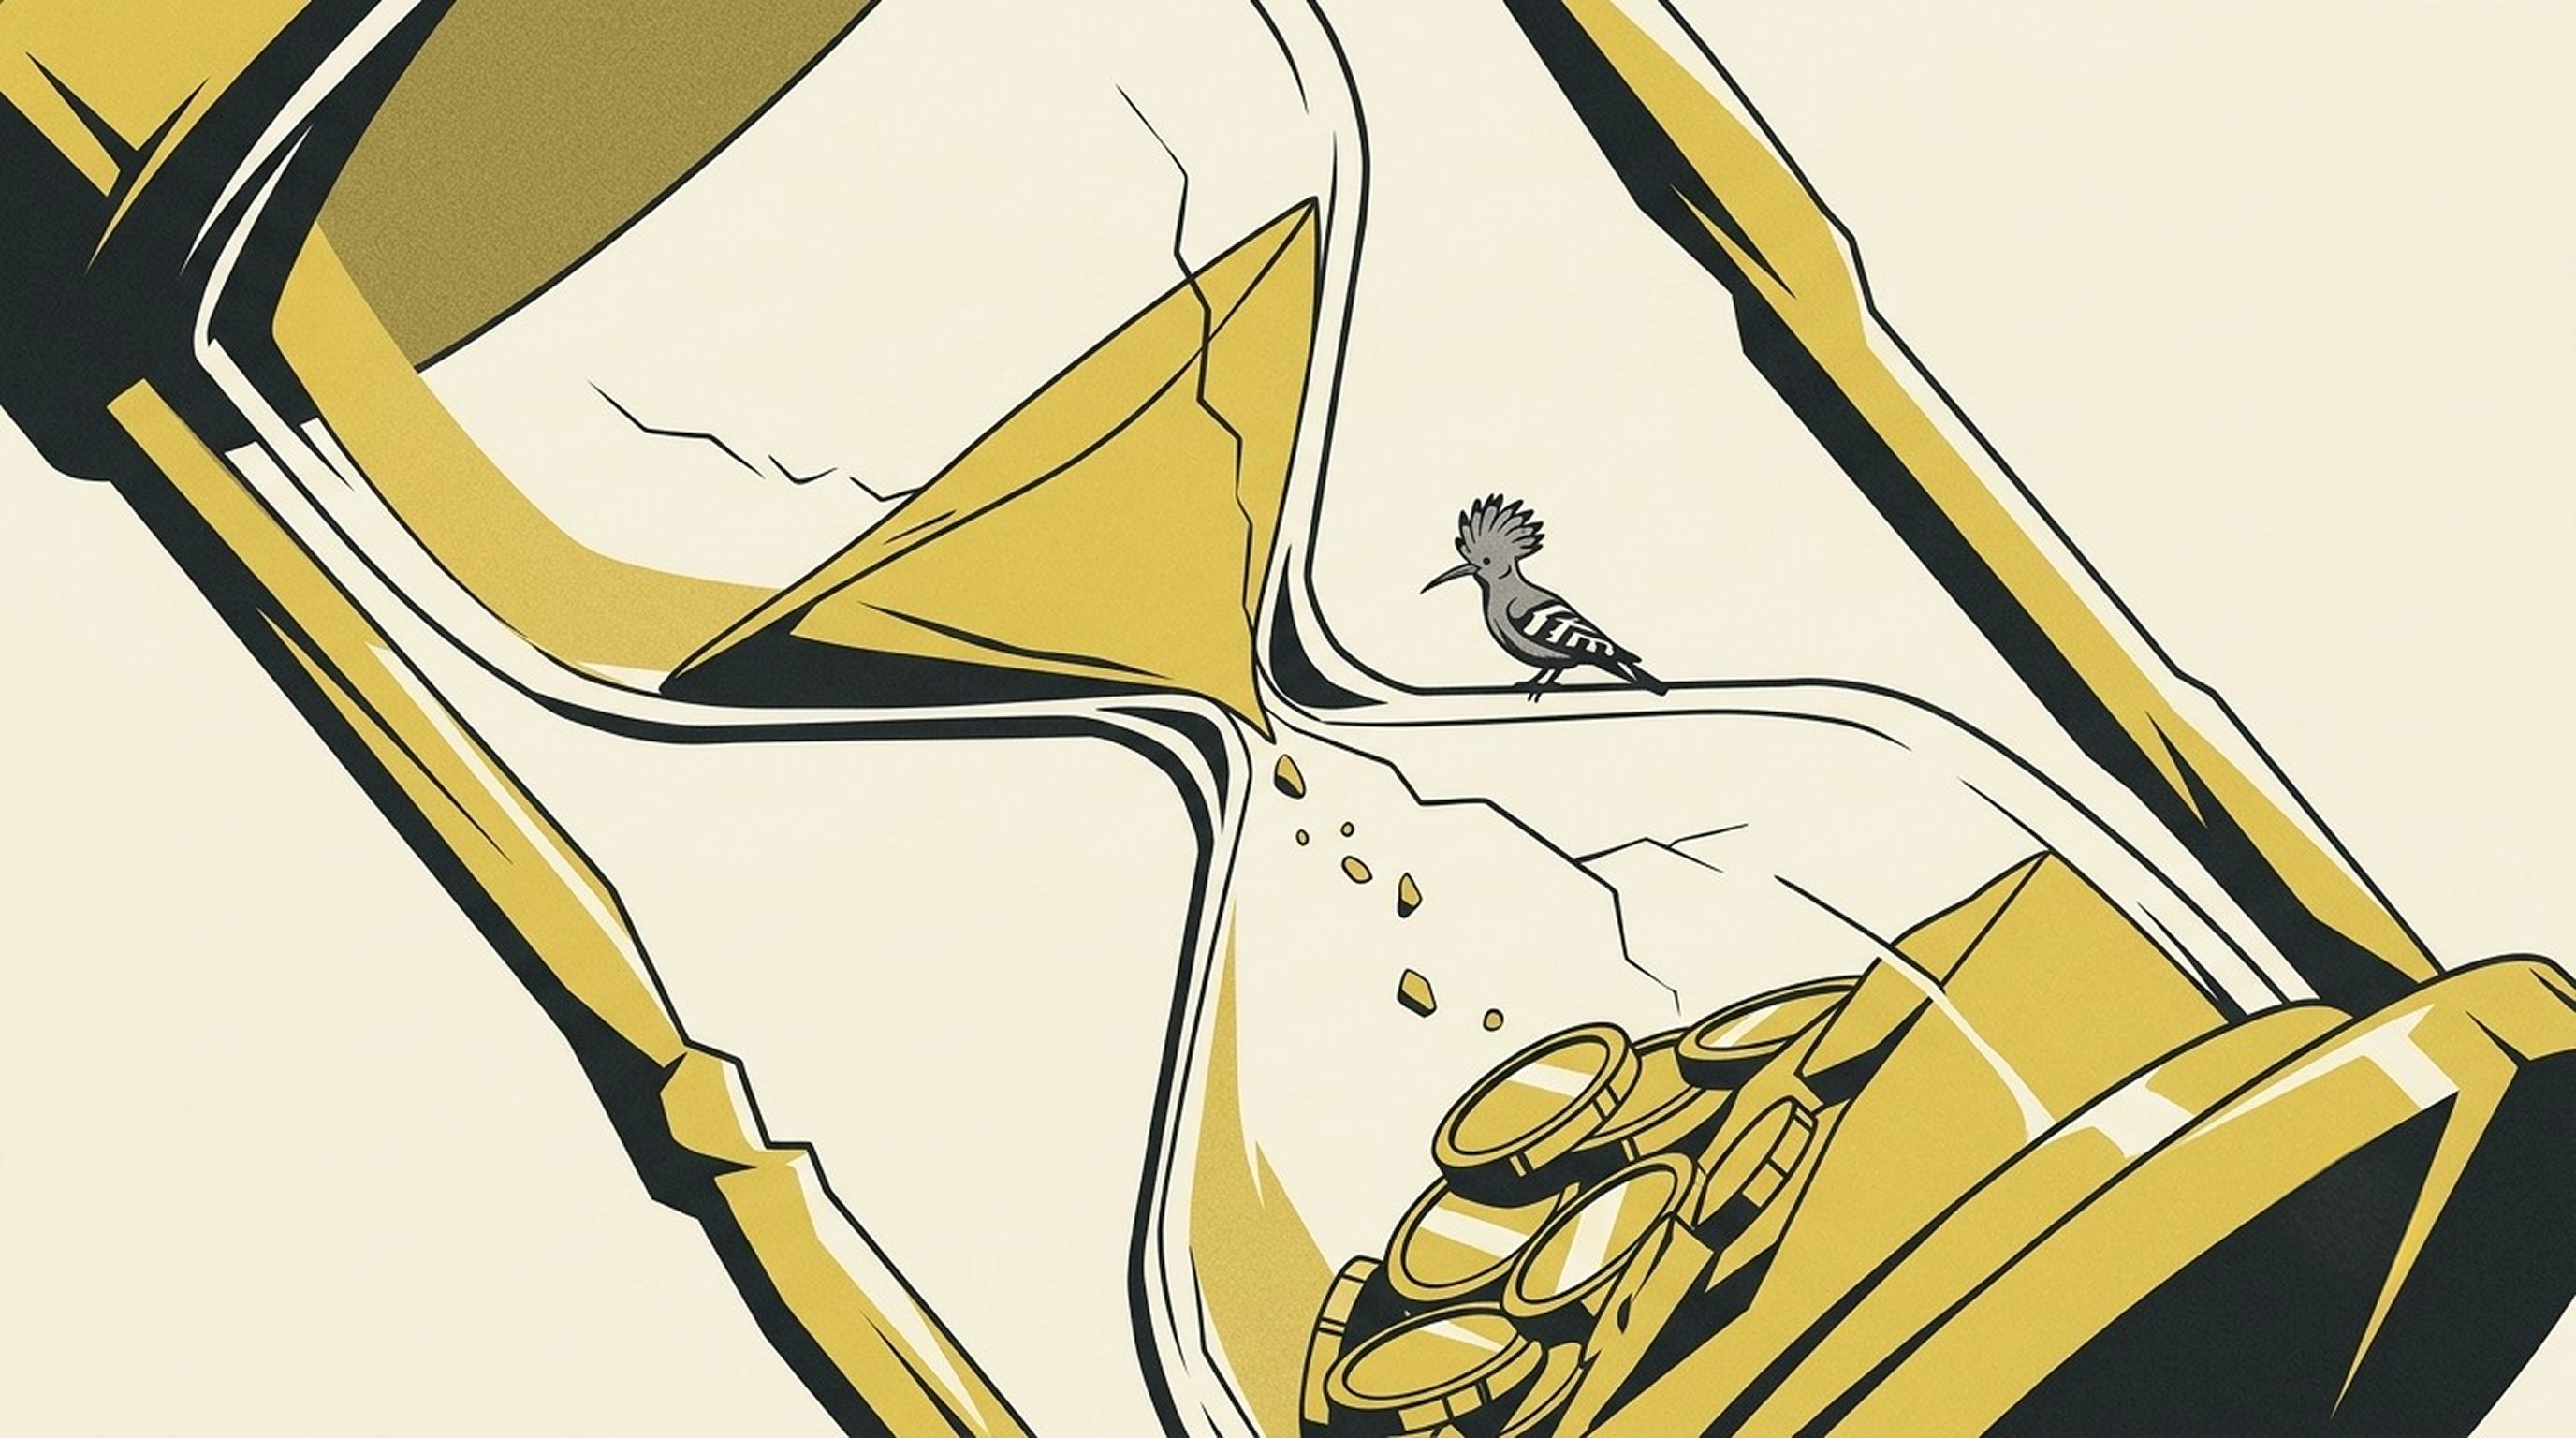
Imagine you are planning to buy fresh fruit at your local weekly market. When you arrive, you notice the stall is showing far less fruit than in previous weeks, and a lot of people are queuing for it. That situation is a live example of scarcity in economics: something we need or want has become insufficiently available to meet everyone's needs.
This simple idea stretches across much wider areas of life, covering the scarcity of money, time, raw materials, housing, and job opportunities.
In this article we explain scarcity clearly, and how it affects our financial decisions from spending and saving through investing, planning for the future, and setting priorities. Awareness of it helps us make wiser financial decisions, and leaves us better prepared for volatile conditions.
What is economic scarcity?
Scarcity means available resources are limited, while our wants and needs appear limitless. We want better housing, healthier food, high-quality education, travel, a new car, and much else. But there are constraints on what we can obtain, because our resources are finite.
Simple examples:
Money: however good your income, you still have wants beyond it.
Time: we have only 24 hours in a day against a long list of tasks, and time given to one hobby is time lost to something else.
Natural resources: land, water, and minerals are limited, which makes some goods more expensive than others.
So when we face scarcity, we are forced to think about priorities and decide what to buy, what to leave, how to invest, and how to save for the future.
Scarcity, supply, and demand
To understand why scarcity moves supply, demand, and then prices, look at two concepts:
- Supply: the quantity of a good or service available in the market
- Demand: how much people want and are able to buy that good or service, which requires both the desire to buy and the money to do it
When a good is in short supply and the number of people wanting it rises, prices rise. If a wheat crop is hit by drought, output falls and market supply drops. But people still need wheat for bread, pasta, and the rest. With less supply against higher relative demand, sellers raise the price.
Conversely, when a good is abundant, such as certain vegetables in season, high supply against stable demand pushes prices down, because sellers want to move stock before it spoils.
This relationship between scarcity, supply, demand, and price matters, because it determines what we pay for what we need. Once you understand that price rises are not random but the result of a balance between availability and desire, you can calibrate your expectations and make better financial decisions.
How scarcity affects daily financial decisions
Because of scarcity, we cannot easily buy everything we want. Our financial resources, whatever their size, have limits. That creates a challenge in how we manage money. For example:
Adjusting spending habits: when prices of essentials rise because of scarcity, we may reduce the quantities we buy, choose cheaper brands, or postpone non-essential purchases.
Saving for the future: when we worry about continuing price rises driven by scarce resources, or about unstable markets, we start seriously allocating part of our income to saving. Saving gives us a sense of financial security and helps us face conditions that may be harder later.
Looking for suitable investments: scarcity also pushes us to consider the best ways to invest. If cash is losing value to inflation, which is a general and sustained rise in prices, we may consider property, gold, a promising company, or an account that generates a regular return, in order to protect purchasing power.
Scarcity and opportunity cost
Suppose you have a sum of money and two options: buy a new smartphone, or invest it in a small business. Choose the phone and the alternative cost is the chance to invest. Choose the investment and you lose the enjoyment of the technology the phone offers. You cannot do both at once.
That is opportunity cost. In a world of scarcity, every financial decision comes at the expense of other choices you could have made. We have limited resources against multiple options, and we have to pick just one, and every choice means leaving others behind.
Understanding this makes you think carefully before spending: what benefit will I get now, what am I giving up in return, and does this option deliver the most possible benefit from the money I have?
Why financial awareness matters here
Financial awareness means understanding how markets work, how scarcity affects prices, and how to decide more intelligently in light of that. When we know these things, we become better at:
Evaluating options: we can compare offers and choose the best on value and quality.
Anticipating risk: knowing scarcity may push some prices higher later, we take precautions such as saving or buying certain goods before prices rise.
Diversifying income and investments: rather than relying on a single income source, we look for additional ones, or spread savings across several investments to protect ourselves from economic shocks.
Setting financial priorities under scarcity
Scarcity forces us to order priorities. Not everything we want is necessary, and not everything we want is affordable at any given moment. When facing a difficult financial position, ask yourself:
- What are the essentials I cannot live without, such as food, housing, and treatment?
- What can I postpone, such as a new car or replacing furniture?
- What can I do without, such as luxuries that add no real long-term value to my life?
Setting priorities makes sure we use limited resources on what matters most, which preserves stability and keeps us out of sharp financial crises.
Financial planning to adapt to scarcity
Financial planning is the process of setting an organized plan for what we will do with money today and in the future. Once we understand scarcity and why it matters, we see that planning is essential.
Financial planning includes:
- Building a monthly budget: identifying income sources and expenses
- Setting long-term financial goals: saving to buy a home, educate children, or fund a comfortable retirement
- Diversifying investments: rather than putting all savings in one place, splitting them across more than one area to reduce risk
- Periodic review: checking the plan regularly to confirm you are on track, and correcting anything that has drifted
With good planning, we handle scarcity intelligently, maximise the benefit available from what we own, prepare for potential risks, and always keep alternative plans in place.
Scarcity, saving, and investing
When resources thin out and market supply drops, prices rise automatically. In that case we may have to spend a larger share of income on essentials, which reduces what is available to save. At the same time, many people feel a stronger need to save when they doubt future price stability. One of us might say: better to save now even in hard conditions, so I know I have enough later.
On investing, scarcity can create new opportunities. When a resource becomes tight, new industries may emerge to supply alternatives, or opportunities may appear in sectors that were not previously interesting. If traditional energy sources become scarce and their prices rise, good opportunities may open in renewable energy. In that sense scarcity is not always negative, it can open doors to innovation and push exploration of new fields.
What scarcity teaches
Everyone passes through moments where the resources around them feel limited, whether in money, time, or capability. Handling those situations well teaches real skills:
Flexibility: when money is short, we learn to be flexible in our consumption habits and to find new ways to adapt.
Creativity: finding alternative solutions, such as growing vegetables on a balcony, or repairing things instead of replacing them.
Contentment: many people discover under scarcity that they can live happily with fewer resources, which strengthens their satisfaction and appreciation for what they have.
 Conclusion
Scarcity is not a complicated economic concept, it is a reality we touch daily. It affects the price of goods and makes us think hard about how we spend, save, and invest. Awareness of it, and of how markets work, gives us the ability to handle difficult conditions with less stress, and helps us build specific financial plans and prepare for future changes.
In the end, although scarcity looks like an obstacle, it is also an opportunity to develop our financial skills and improve our capacity for wise decisions. When we understand it, we become better able to control our limited resources, and to turn the challenge into a driver of personal economic growth and long-term financial stability.
PhD in Islamic Economics & Banking and a certified CSAA (Certified Shari'ah Advisor & Auditor)
Read also
Navigate Financial Freedom with Chess Mindset
End the cycle of spending guilt and learn how to manage your finances with a simple, stress-free plan.
 6 min read
Your Route to Financial Freedom: A Glossary of the Concepts That Get You There
Financial literacy is one of those phrases that sounds impressive and explains nothing on its own. This article maps the core concepts you need in your toolkit, from opportunity cost to emergency funds, and it is updated continuously.
5 min read
Ramadan: A Practical Reset for Your Financial Habits
Ramadan is meant to be a month of restraint, yet it has quietly become one of the heaviest spending seasons of the year. This article turns the month into a structured reset for your financial habits, from planning the food budget to giving deliberately and leaving Ramadan without new debt.
8 min read
Download the app now!
Read more through the Xeer app. Download it now and enjoy all Xeer features.
 Download the App

Read also
Beyond "BNPL": The Real Cost of Consumer Installment Finance
Consumer installment finance doesn't just affect the people using it, it reshapes spending behavior, market pricing, and economic stability at scale. This article traces the real cost of BNPL from the individual decision all the way to the broader market, and what to do with that understanding.
 Ahmed El Zoughby
8 min read
Traditional Installments & Commercial BNPL through the lens of Islamic Finance
Installment finance in Egypt takes more than one form, and the differences between them are not in the marketing, they're in the structure. This article breaks down some of those commercial models, what each one hides, and where each one stands against the sharia compliance standards.
Ahmed El Zoughby
7 min read
Buy Now, Pay Later: How Consumer Finance Became Part of Egyptian Life
Consumer installment finance in Egypt is no longer a niche product, it is infrastructure. Understanding what's driving this growth, and what the numbers behind it actually mean, is the starting point for any informed financial decision.
Ahmed El Zoughby
3 min read