

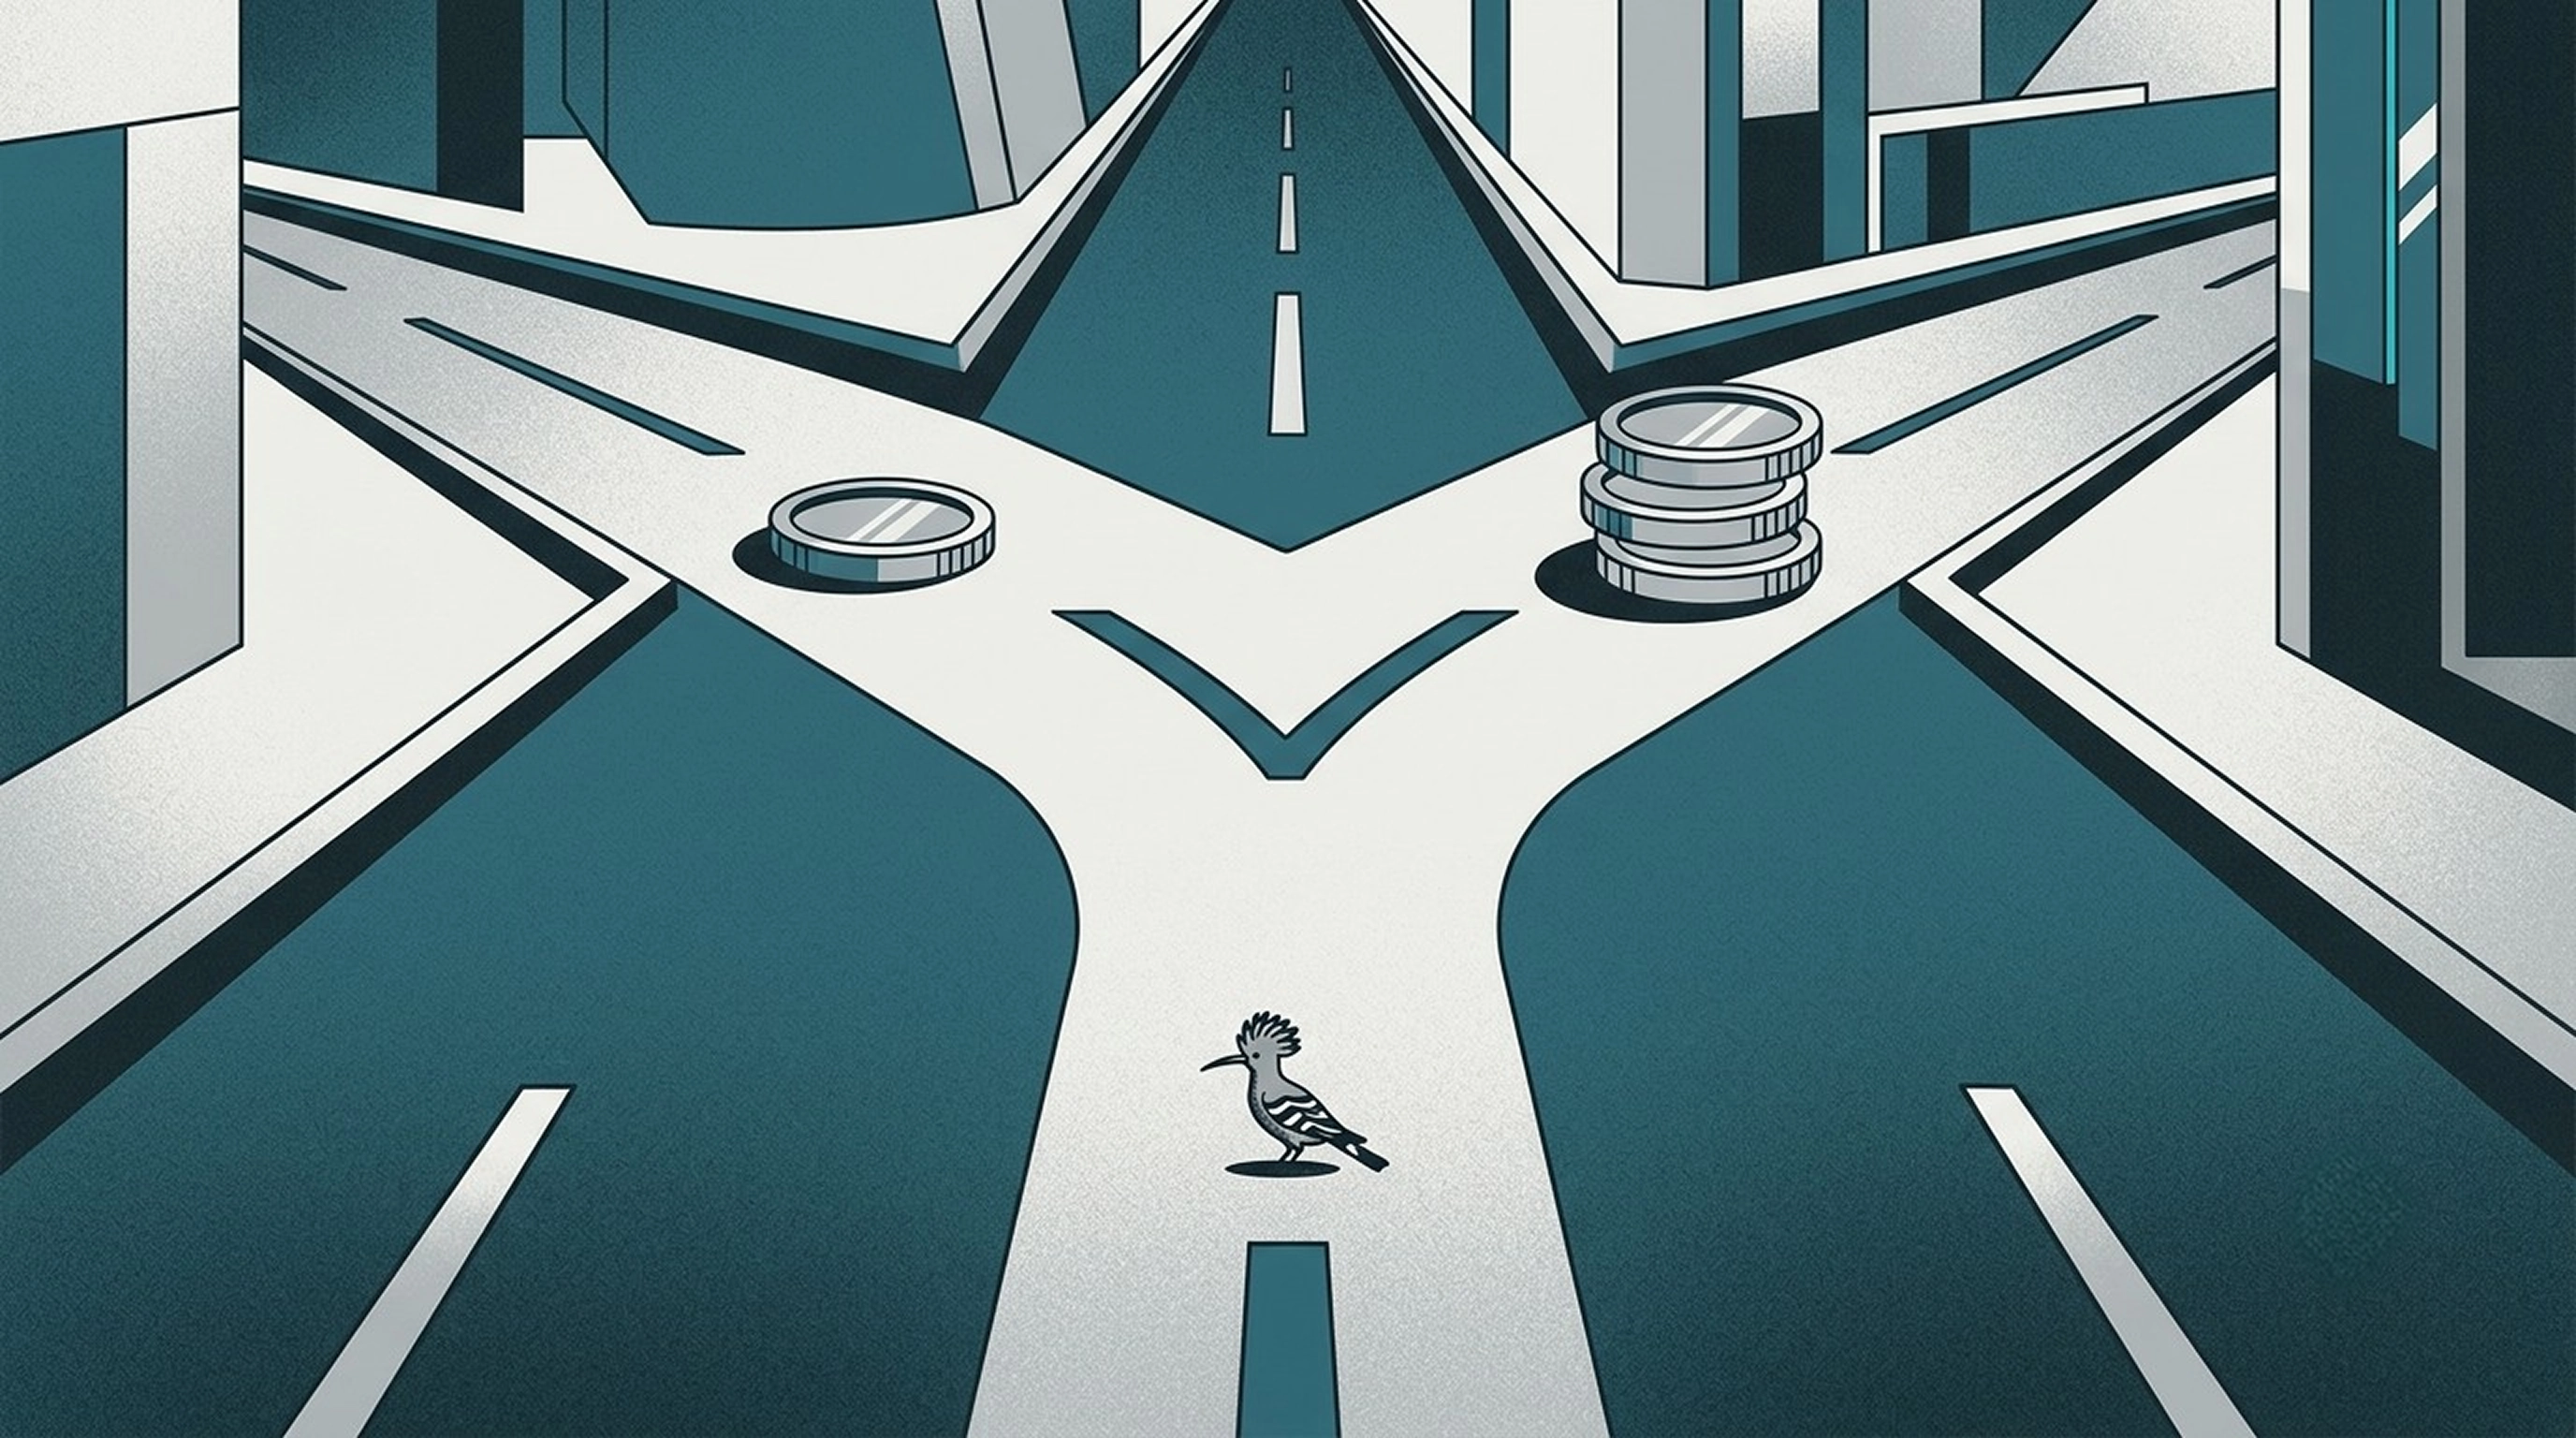
Imagine you have a sum of money and want to either spend or invest it. You have two options: buy a new car, or put it into a small business that generates future returns. Choose the car and you give up the income the business might have produced. Choose the business and you give up the immediate enjoyment of driving a new car. That simple conflict between two options carries an important economic idea: opportunity cost.
Opportunity cost is not a theory studied only by economics students. It is a practical reality we face daily in financial decisions, large and small. This article explains what opportunity cost is, how to calculate it, and why it matters in financial planning and investing. It also walks through real examples, clarifies the difference between explicit and implicit costs, and shows how financial awareness helps you use the concept to decide better.
What is opportunity cost?
Opportunity cost is the value of the opportunity you forfeit when you choose one option over another available one. In other words, it is the benefit or return you would have received had you chosen the alternative. The idea comes out of scarcity: available resources such as money, time, and effort are limited, and we cannot have everything we want at once.
For example, if you have limited time in the evening after work, and you could spend it studying a new skill or watching television, the opportunity cost of watching television is the chance to learn the skill that would have raised your value in the job market. That is how opportunity cost makes us aware of the hidden price we pay for our choices.
Why it matters in financial decisions
Understanding opportunity cost improves the quality of your decisions, because it gives you a clearer picture of what you lose when you choose one thing over another. That lets you balance present and future gains more effectively, and compare options against objective criteria.
How it helps you evaluate options
When you think in terms of opportunity cost, you start with these questions:
- What alternatives are actually available to me?
- What do I lose if I choose this one?
- Is the benefit I'll get from this option the best available?
Answering those helps you assess options with more neutrality. Take a sum of money you are thinking of putting into a savings account with a fixed annual return, or into equities. Choose the savings account and the opportunity cost is the potential gain from equities. Choose equities and you may lose the relatively guaranteed fixed return the savings account offers. Knowing this helps you decide based on the risk level you can carry and your expectations.
Note here that interest earned on a conventional savings account is impermissible from an Islamic perspective, and this is taken into account when choosing between alternatives. You may prefer investing in equities with potential returns over a conventional interest-bearing savings account with a fixed return.
Which shows something important: the evaluation is not purely material. The set of values you hold is part of the assessment.
Practical examples
Buying a home or investing the money: if you have a large sum and are thinking about buying a home to live in, the opportunity cost may be investing it in a business that generates profit. Choose the home and you lose the potential returns. Choose the investment and you may lose housing stability and the rent you would have saved.
Remember: no single choice is best for everyone. We balance our financial needs against our social circumstances.
Choosing a job: you are offered two roles. The first pays well but demands long hours and heavy effort. The second pays less but asks less and leaves more free time. The opportunity cost of the comfortable role is the extra income from the demanding one. The opportunity cost of the demanding role is the free time and rest you give up.
Our core values, and how we express them, always show up in these choices. In the example above, both options relate to family, but the expression differs. If caring for your family means meeting everything they want, the demanding role fits because it produces more money. If spending more time with them is how you express that care, the comfortable role fits. There is no universally correct answer, only a reflection of how each of us lives and thinks.
Education: spending several years at university means spending time, effort, and money. The opportunity cost is the income you could have earned by starting work immediately after secondary school. On the other side, choosing to work directly means losing the chance to raise your qualifications and earn more later on the strength of a degree.
Worth noting: decisions are not always fully independent or purely black and white. There is often a grey area where a mix works. In the example above, you could work part-time to build market skills and earn an income while completing your studies.
Opportunity cost in personal financial planning
When building financial plans, short or long term, opportunity cost belongs in the calculation. When building a personal budget, you may allocate part of income to saving, part to essentials, and part to discretionary spending. Spend more on the discretionary side and you reduce your capacity to save and invest, and the reverse holds too.
It shapes daily decisions as well, because the value of the money in your hands is set by how you use it. The unit of currency you spend on bread carries more benefit than the one you spend on coffee on the way to work, even though they are theoretically identical in form and value.
Recognising opportunity cost teaches you to balance present wants against future needs. It also helps you order priorities: is it better to clear debt early, or to put the money into an investment opportunity? Do I allocate more savings to my children's education, or invest it in a project that may raise their standard of living later?
Explicit costs versus implicit costs
To understand opportunity cost properly, separate two kinds of cost:
Explicit costs: what you pay directly out of pocket. Buy a machine at a given price, and that amount is an explicit cost.
Implicit costs: the invisible or indirect costs you don't pay in cash, but which reflect the loss from not using another alternative. If you spend free time watching television instead of studying a new skill, you pay no money, but you lose the chance to raise your value in the market. That is an implicit loss.
Opportunity cost usually includes implicit costs, because it represents unused opportunities. Understanding the difference helps you identify the true value of your choice, not only the costs that appear on the surface.
Opportunity cost in investing
In investing, this matters enormously. Imagine you have a sum and several options:
- Put the money in a savings account with a low but safe return
- Invest in shares of startups that could produce large gains or losses
- Buy government bonds with a fixed return that is lower than the potential equity return
- Invest in property that may appreciate
Each case carries an opportunity cost. Choose the safe account and you lose potential gains from equities or property. Choose equities and you may lose the security bonds or savings accounts offer. Understanding these trade-offs clearly helps you pick the instruments that fit your goals, your values, and the risk you can carry.
How to calculate it
This doesn't require a complex formula, it is an analytical exercise. Suppose you face two decisions:
- Decision A: produces benefit or profit of X
- Decision B: produces benefit or profit of Y
Choose A, and the opportunity cost is Y. Choose B, and it is X.
It gets more complex with more than two options, and when you factor in risk, time, quality of life, and personal criteria. With multiple options, the opportunity cost is the second-best option, assuming you have ranked them from most to least beneficial. The principle stays the same: compare what you get against what you lose by not taking another path.
Opportunity cost, scarcity, and choice
Scarcity means resources are limited. With limited resources, we are always forced to choose between alternatives. The scarcer the resource, the more opportunity cost matters, because our choice may forfeit another important opportunity. Time is an extremely scarce resource: every hour spent on one activity denies us another that would have delivered a different benefit. That link between scarcity and choice is what makes opportunity cost fundamental to economics.
The role of financial awareness
Financial awareness means understanding how markets, resources, and money work around you, and being able to make informed decisions on that basis. When you recognise opportunity cost, you become able to:
Evaluate financial options objectively: you stop looking only at what you gain from the current decision, and start thinking about the other opportunities you forfeit.
Plan for the future more wisely: understanding opportunity cost helps you set clear financial goals and build balanced plans that account for both present and future needs.
Reduce regret over decisions: when you make a financial decision after weighing opportunity cost, you have more confidence that you chose what suits you, which lowers the chance of regret later.
 Conclusion
Opportunity cost is a simple idea with powerful effects. It reminds you constantly that every choice involves giving something else up. Understanding that principle improves the quality of your financial decisions and lets you assess the true price of any action, whether you are buying something, investing money, or allocating time. It is not a number or an equation, it is a way of thinking that makes you more aware and more careful with limited resources.
By knowing the opportunities you forfeit when deciding, you become better able to control how you handle money, and to strike a better balance between what you do now and what you give up in return. That perspective builds a solid financial foundation, sharpens your financial management and planning skills, and secures a more stable and satisfying life over the long term.
PhD in Islamic Economics & Banking and a certified CSAA (Certified Shari'ah Advisor & Auditor)
Read also
Navigate Financial Freedom with Chess Mindset
End the cycle of spending guilt and learn how to manage your finances with a simple, stress-free plan.
 6 min read
Your Route to Financial Freedom: A Glossary of the Concepts That Get You There
Financial literacy is one of those phrases that sounds impressive and explains nothing on its own. This article maps the core concepts you need in your toolkit, from opportunity cost to emergency funds, and it is updated continuously.
5 min read
Ramadan: A Practical Reset for Your Financial Habits
Ramadan is meant to be a month of restraint, yet it has quietly become one of the heaviest spending seasons of the year. This article turns the month into a structured reset for your financial habits, from planning the food budget to giving deliberately and leaving Ramadan without new debt.
8 min read
Download the app now!
Read more through the Xeer app. Download it now and enjoy all Xeer features.
 Download the App

Read also
Beyond "BNPL": The Real Cost of Consumer Installment Finance
Consumer installment finance doesn't just affect the people using it, it reshapes spending behavior, market pricing, and economic stability at scale. This article traces the real cost of BNPL from the individual decision all the way to the broader market, and what to do with that understanding.
 Ahmed El Zoughby
8 min read
Traditional Installments & Commercial BNPL through the lens of Islamic Finance
Installment finance in Egypt takes more than one form, and the differences between them are not in the marketing, they're in the structure. This article breaks down some of those commercial models, what each one hides, and where each one stands against the sharia compliance standards.
Ahmed El Zoughby
7 min read
Buy Now, Pay Later: How Consumer Finance Became Part of Egyptian Life
Consumer installment finance in Egypt is no longer a niche product, it is infrastructure. Understanding what's driving this growth, and what the numbers behind it actually mean, is the starting point for any informed financial decision.
Ahmed El Zoughby
3 min read